Credit Assessment Report: Key Indicators for Evaluating Business Creditworthiness
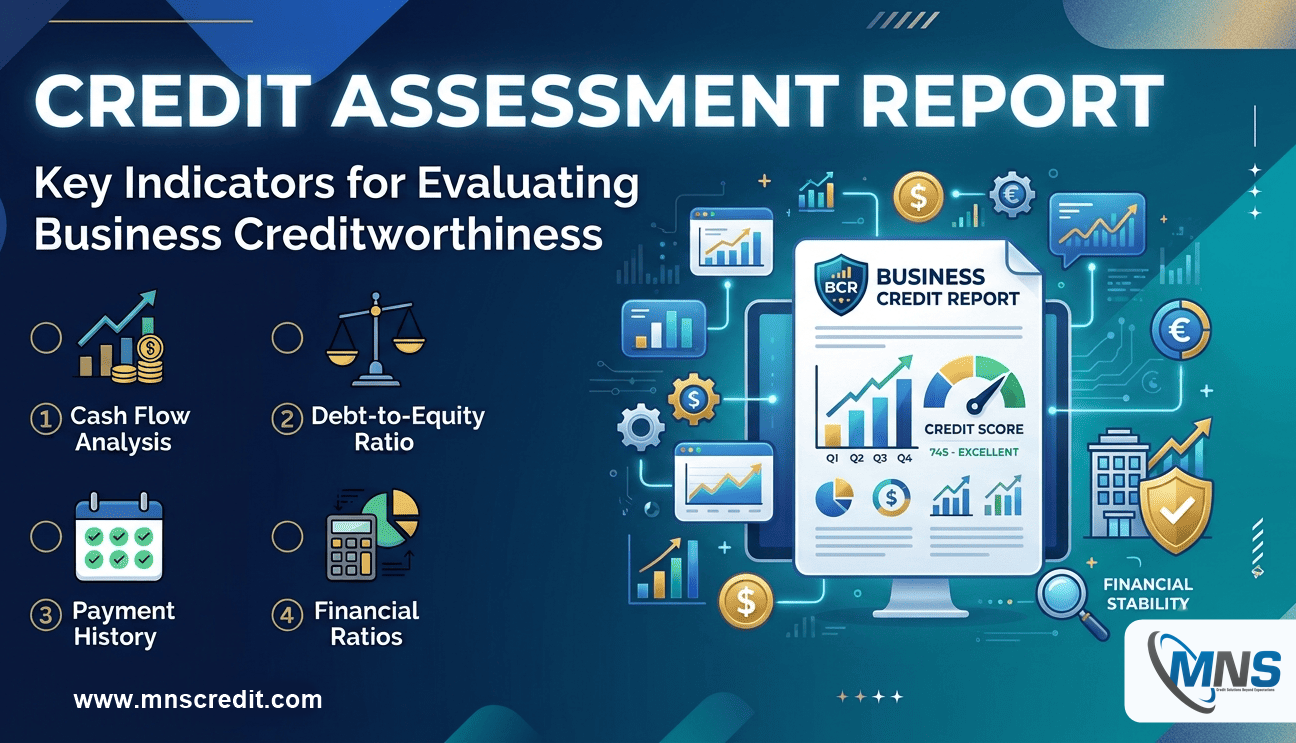
Extending credit is one of the most common ways businesses win customers, and one of the most common ways they lose cash. When a buyer pays late or not at all, the cost goes beyond the unpaid invoice. Working capital tightens, planning suffers, and teams end up spending time on debt collection instead of growth. A credit assessment report is the first line of defence against that outcome. It gives decision-makers a structured, evidence-based view of a company’s ability and willingness to pay before any exposure is created.
What Is a Credit Assessment Report?
A credit assessment report is a consolidated evaluation of a business’s financial strength, payment behaviour, legal standing and operating stability. It draws on financial statements, bureau data, regulatory filings, trade references and public records, and turns them into a clear view of risk. Lenders, underwriters, credit managers and procurement teams use it to set credit limits, define payment terms and decide whether to proceed with a relationship at all.
A well-prepared report does more than label a company “good” or “bad”. It shows where the strengths and weaknesses lie, so that credit decisions can be calibrated rather than binary.
Key Indicators for Evaluating Business Creditworthiness
1. Financial Statements and Ratio Analysis
Audited financial statements remain the foundation of any assessment. Analysts typically examine three groups of ratios:
- Liquidity ratios, such as the current ratio and quick ratio, show whether the company can meet short-term obligations.
- Leverage ratios, such as debt-to-equity and interest coverage, show how heavily the business relies on borrowing and whether earnings comfortably service that debt.
- Profitability and efficiency ratios, such as net margin, return on capital and receivables turnover, show whether the business generates sustainable returns and collects its own dues on time.
Trends matter as much as absolute numbers. A company with modest ratios that are improving year on year may be a safer bet than one with strong ratios that are steadily deteriorating.
2. Payment History and Credit Behaviour
Past behaviour is among the best predictors of future payment performance. Credit bureau data, trade references and supplier feedback reveal how a company treats its obligations in practice. Frequent delays, rising days-beyond-terms, disputed invoices and a growing number of creditors chasing payment are early signs of stress. Businesses that already require frequent debt collection follow-up from their suppliers are likely to need the same from you.
3. Cash Flow Strength
Profit on paper does not pay bills; cash does. Operating cash flow, free cash flow and the cash conversion cycle show whether a company generates enough liquidity from its core activities. Heavy reliance on short-term borrowing to fund day-to-day operations, or a widening gap between reported profit and operating cash flow, deserves close scrutiny.
4. Legal and Regulatory Standing
Corporate records provide an objective check on a company’s legitimacy and compliance. In India, MCA21 filings reveal registered details, directors, charges on assets, filing regularity and company status. Analysts should also check for:
- Pending litigation, particularly recovery suits and cheque dishonour cases
- Insolvency or winding-up proceedings under the Insolvency and Bankruptcy Code
- Tax and statutory compliance, including GST and income tax filings
- Adverse regulatory actions or sanctions exposure
A company that is struck off, non-compliant or facing insolvency proceedings presents a very different risk profile from one with clean records.
5. Ownership and Management Quality
Who owns and runs a business shapes how it behaves under pressure. A credit assessment report should map the ownership structure, identify ultimate beneficial owners and review the track record of directors and key managers. Links to defaulted entities, frequent board changes or opaque shareholding structures are warning signs. Stable, experienced and transparent management generally signals stronger governance and a greater willingness to honour commitments.
6. Industry and Market Conditions
No company operates in isolation. Sector cyclicality, input cost volatility, regulatory change, customer concentration and competitive pressure all affect repayment capacity. A financially sound company in a declining sector may still deserve tighter terms, while a leaner company in a growing market may merit more flexibility.
7. Collateral, Guarantees and Credit Enhancements
Where exposure is significant, security can change the risk equation. Personal guarantees, corporate guarantees, letters of credit and trade credit insurance reduce the loss given default. The report should assess both the quality of the security offered and how easily it could be enforced.
From Assessment to Action
Collecting these indicators is only useful if they feed into a clear decision framework. Many organisations convert findings into an internal credit score or risk grade, which then drives credit limits, payment terms and monitoring frequency. High-risk customers may be offered advance payment or secured terms, while low-risk customers can receive open credit.
Assessment should also continue after approval. Financial conditions change, so periodic reviews and automated alerts on filings, litigation or bureau changes help detect deterioration before invoices become overdue. Early warning allows you to act while options are still open, for example by reducing limits, tightening terms or opening a conversation with the customer.
Why Strong Assessment Reduces Debt Collection Costs
Effective debt collection is far easier, faster and cheaper when it begins with sound credit decisions. Customers screened properly are less likely to default, and where default does occur, thorough documentation of the customer’s financial position, legal identity and assets makes recovery more practical. The information gathered in a credit assessment report, such as verified registered details, directors, asset charges and prior payment behaviour, becomes valuable evidence if the matter later requires negotiation, legal notice or formal recovery proceedings.
Businesses that treat credit assessment as a preventive discipline typically spend less on collections, write off fewer receivables and maintain healthier cash flow. Those that skip it often find that debt collection becomes a costly, reactive exercise with uncertain outcomes.
Conclusion
A credit assessment report brings together financial health, payment behaviour, cash flow, legal standing, management quality, industry conditions and security into one clear picture of risk. Evaluating these indicators consistently allows businesses to extend credit with confidence, protect working capital and reduce dependence on debt collection after the fact. In a market where late payments and defaults can quickly erode margins, informed credit decisions are not an administrative step but a strategic advantage.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek