How to Turn Your 401(k) Into a Stronger Retirement Strategy
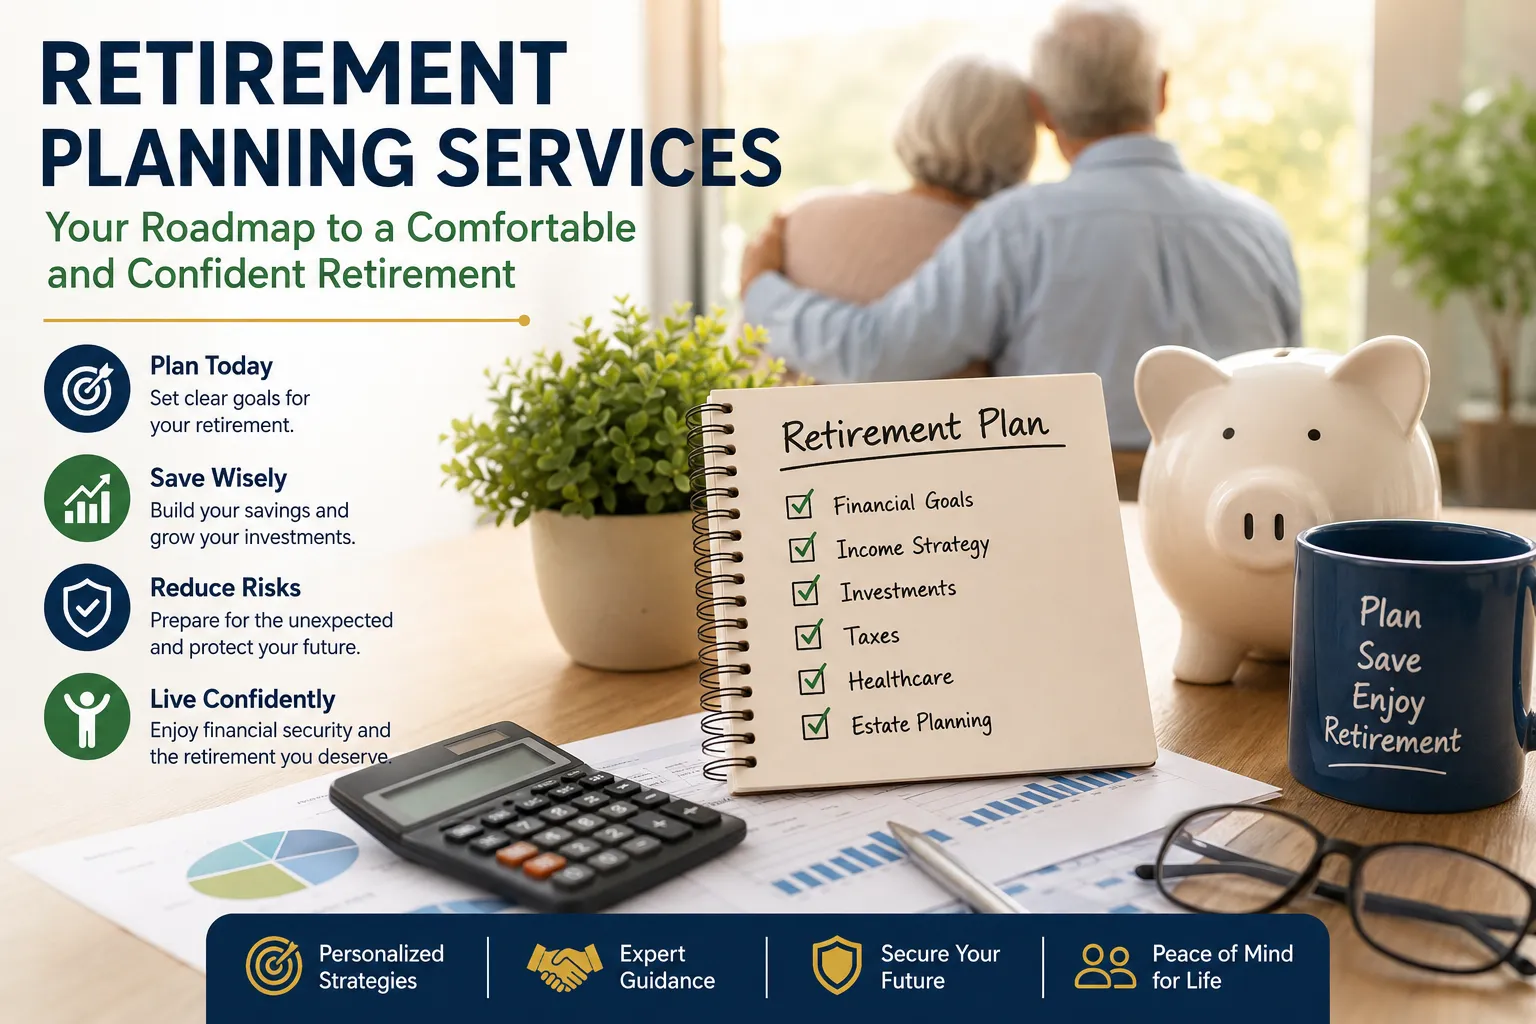
Retirement planning is more than deciding how much money to save each month. You also need to understand where your savings are invested, how much income you may need later, and how your financial decisions today could affect your future lifestyle.
For many employees, a 401(k) is one of the most important retirement savings tools available. Yet simply contributing to a workplace plan does not automatically create a complete retirement strategy. Your contributions, investment choices, risk level, expected retirement age, taxes, healthcare costs, and other savings all need to work together.
A thoughtful approach to a 401k retirement plan can help you identify gaps early and make more informed decisions before retirement arrives.
Start by Defining What Retirement Means to You
A common retirement-planning mistake is focusing on a savings number without first considering what you want your retirement to look like.
Will you continue working part-time? Do you want to travel frequently? Will you relocate? Are you planning to help children or grandchildren financially? Do you expect significant healthcare or housing expenses?
These questions matter because retirement expenses vary considerably from person to person.
Create a realistic estimate of your future spending by separating expenses into categories such as:
- Housing and utilities
- Food and transportation
- Healthcare and insurance
- Travel and entertainment
- Personal expenses
- Taxes
- Emergency and unexpected costs
Having a clearer picture of future spending gives your savings target more meaning.
Make Your 401(k) Work With Your Overall Plan
A workplace retirement account should not be viewed in isolation. Your financial picture may also include individual retirement accounts, taxable investments, savings accounts, real estate, business interests, pensions, or other sources of future income.
The purpose of retirement planning is to coordinate these resources.
For example, one person may rely heavily on a workplace plan, while another may have substantial taxable investments and other retirement income. Their investment strategies and withdrawal approaches may therefore look very different.
Reviewing all your accounts together can make it easier to understand your total retirement resources and identify potential weaknesses.
Review Your Contribution Strategy
One of the simplest ways to strengthen retirement savings is to review how much you are contributing.
If your income increases, consider whether your retirement contributions should increase as well. Automatic contribution increases can also help you gradually save more without requiring a major change to your monthly budget.
If your employer provides matching contributions, understand the plan's rules and make sure you know how your contributions interact with the available match.
At the same time, avoid contributing so much that you create problems with essential expenses or high-interest debt. Retirement savings should be part of a balanced financial strategy rather than a decision made without considering your current financial needs.
Pay Attention to Investment Allocation
Saving money is only one part of retirement preparation. The money inside your retirement account also needs an investment strategy.
Your investment allocation should reflect your:
- Age and expected retirement date
- Risk tolerance
- Financial goals
- Other investments
- Expected retirement income
- Ability to withstand market declines
Younger investors with decades before retirement may have a different allocation from someone approaching retirement. However, age alone should not determine an investment strategy.
Diversification can help spread exposure across different investments and asset classes. It does not remove market risk, but it can reduce the impact of relying too heavily on one type of investment.
Avoid Making Emotional Decisions During Market Declines
Market downturns can be especially stressful when retirement is approaching. Seeing an account balance decline may create a strong temptation to move everything into cash.
The problem is that reacting emotionally can interfere with a long-term investment strategy.
Instead of making decisions based solely on recent market movements, review your investment allocation and financial objectives. Determine whether the decline represents a reason to adjust your strategy or simply normal market volatility.
A well-designed plan should account for periods when investments lose value.
Don't Forget About Inflation
Retirement may last for decades, which makes inflation an important planning consideration.
An expense that seems manageable today may become considerably more expensive in the future. Housing, food, healthcare, transportation, and other everyday costs can all increase over time.
This means your retirement strategy needs to consider both today's purchasing power and future spending needs.
Inflation is one reason simply keeping all retirement savings in low-growth assets may not always provide the long-term growth needed to support future expenses. The appropriate balance between growth and stability depends on the individual investor.
Create a Retirement Income Strategy
Accumulating savings and using those savings are two different financial challenges.
Before retirement, you may focus on contributions and portfolio growth. Once retirement begins, the focus often shifts toward generating sustainable income while managing investment risk.
Your income strategy may involve several sources, including:
- 401(k) withdrawals
- IRA distributions
- Social Security benefits
- Pension income
- Taxable investment accounts
- Part-time or business income
- Other personal assets
The order and timing of withdrawals can have tax and investment implications. This is why retirement financial planning should include an income strategy rather than stopping once you reach your savings goal.
Account for Healthcare and Long-Term Costs
Healthcare is another expense that should be included in financial planning for retirement.
Medical expenses can be difficult to predict, particularly during later retirement years. Depending on your circumstances, you may need to consider insurance premiums, deductibles, prescriptions, dental care, vision care, and potential long-term care expenses.
Building an emergency reserve and reviewing available insurance options can make your retirement plan more resilient.
Revisit Your Plan as Your Life Changes
Retirement planning is not a one-time task.
Your income, family circumstances, investment portfolio, retirement date, and financial priorities can change over time. A plan that made sense several years ago may need adjustments today.
Consider reviewing your strategy after major events such as:
- A career change
- A significant increase or decrease in income
- Marriage or divorce
- A major inheritance
- Starting a business
- A change in retirement timing
- A significant market shift
- Major changes in expected expenses
Regular reviews help ensure your retirement strategy remains connected to your current circumstances.
When Professional Guidance Can Help
Retirement planning becomes more complicated as you accumulate multiple accounts, investments, and income sources. Professional guidance can help you evaluate the bigger picture instead of making isolated financial decisions.
When evaluating a financial professional, ask how they approach investment risk, retirement income, tax considerations, portfolio diversification, and changing financial goals.
You can also look for personalized retirement planning guidance when you need help turning individual savings decisions into a coordinated long-term strategy.
Build Your Retirement Plan Before You Need It
A stronger retirement strategy does not require predicting the future perfectly. It requires preparation, regular reviews, realistic assumptions, and disciplined decisions.
Your 401(k) can be an important foundation, but it should work alongside your other assets, income sources, and financial goals. By reviewing contributions, investment allocation, inflation risk, healthcare costs, and future withdrawals, you can identify potential problems while there is still time to address them.
The most valuable part of retirement planning is often starting early enough to make adjustments. Whether retirement is decades away or approaching soon, a clear strategy can help you make better decisions with the resources you have today.

 English
 Arabic
 French
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek